Over the past few 天数, I’ve spoken with several 中小企业 founders about 损益表, 资产负债表, and LHDN readiness. Most agree financial reporting needs to improve.
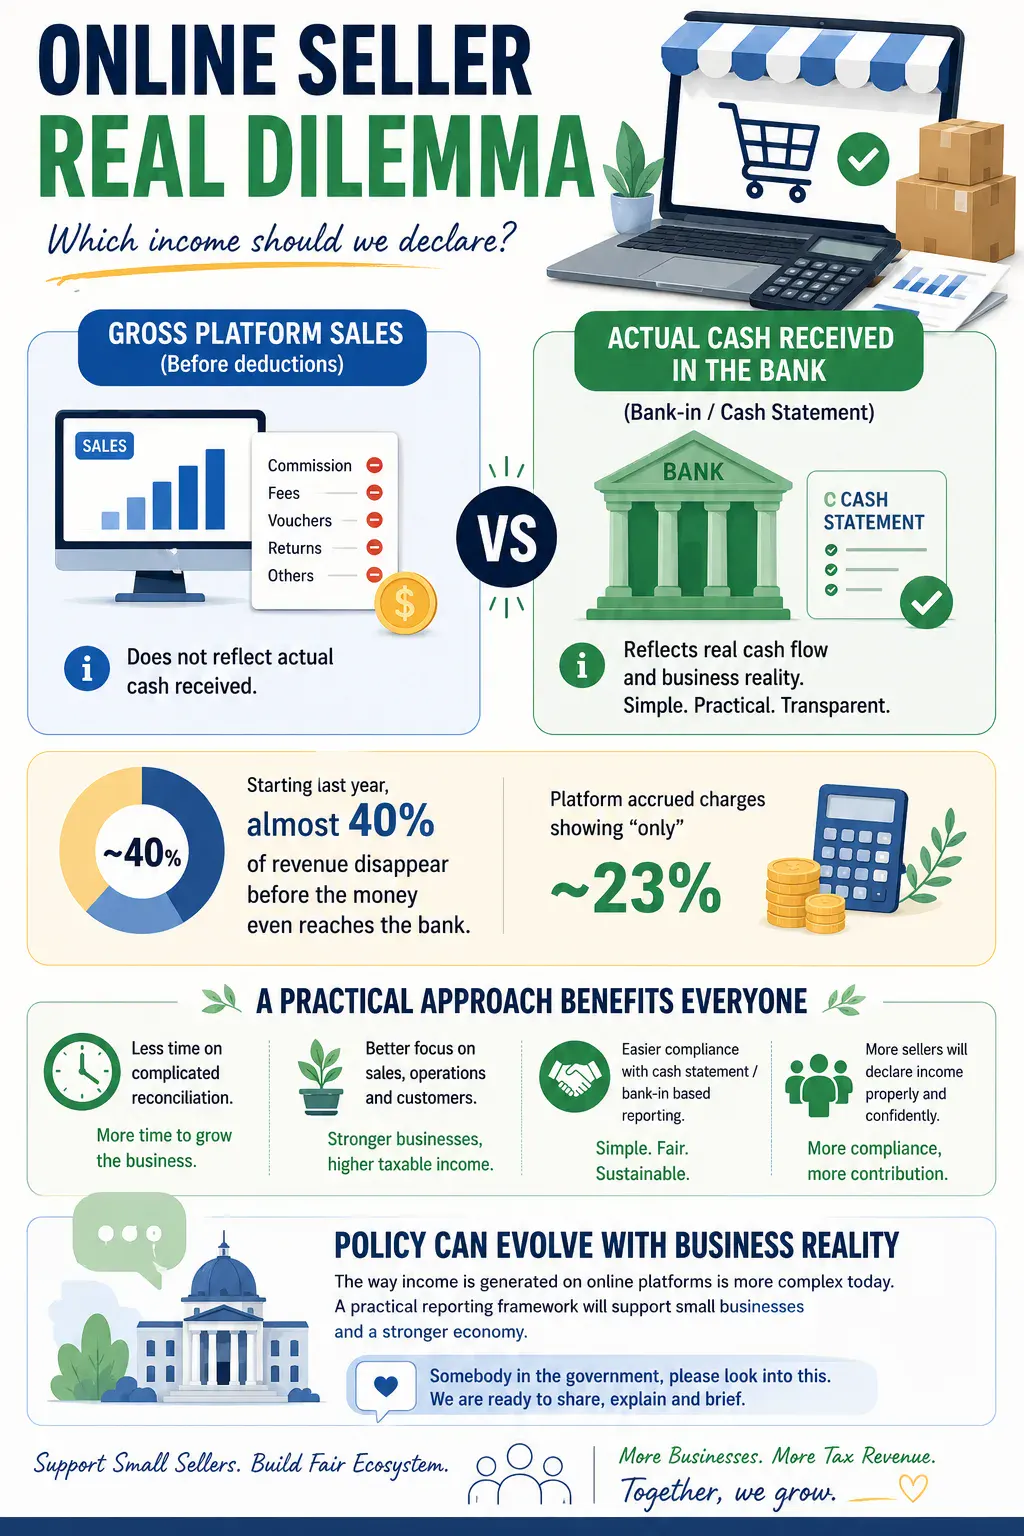
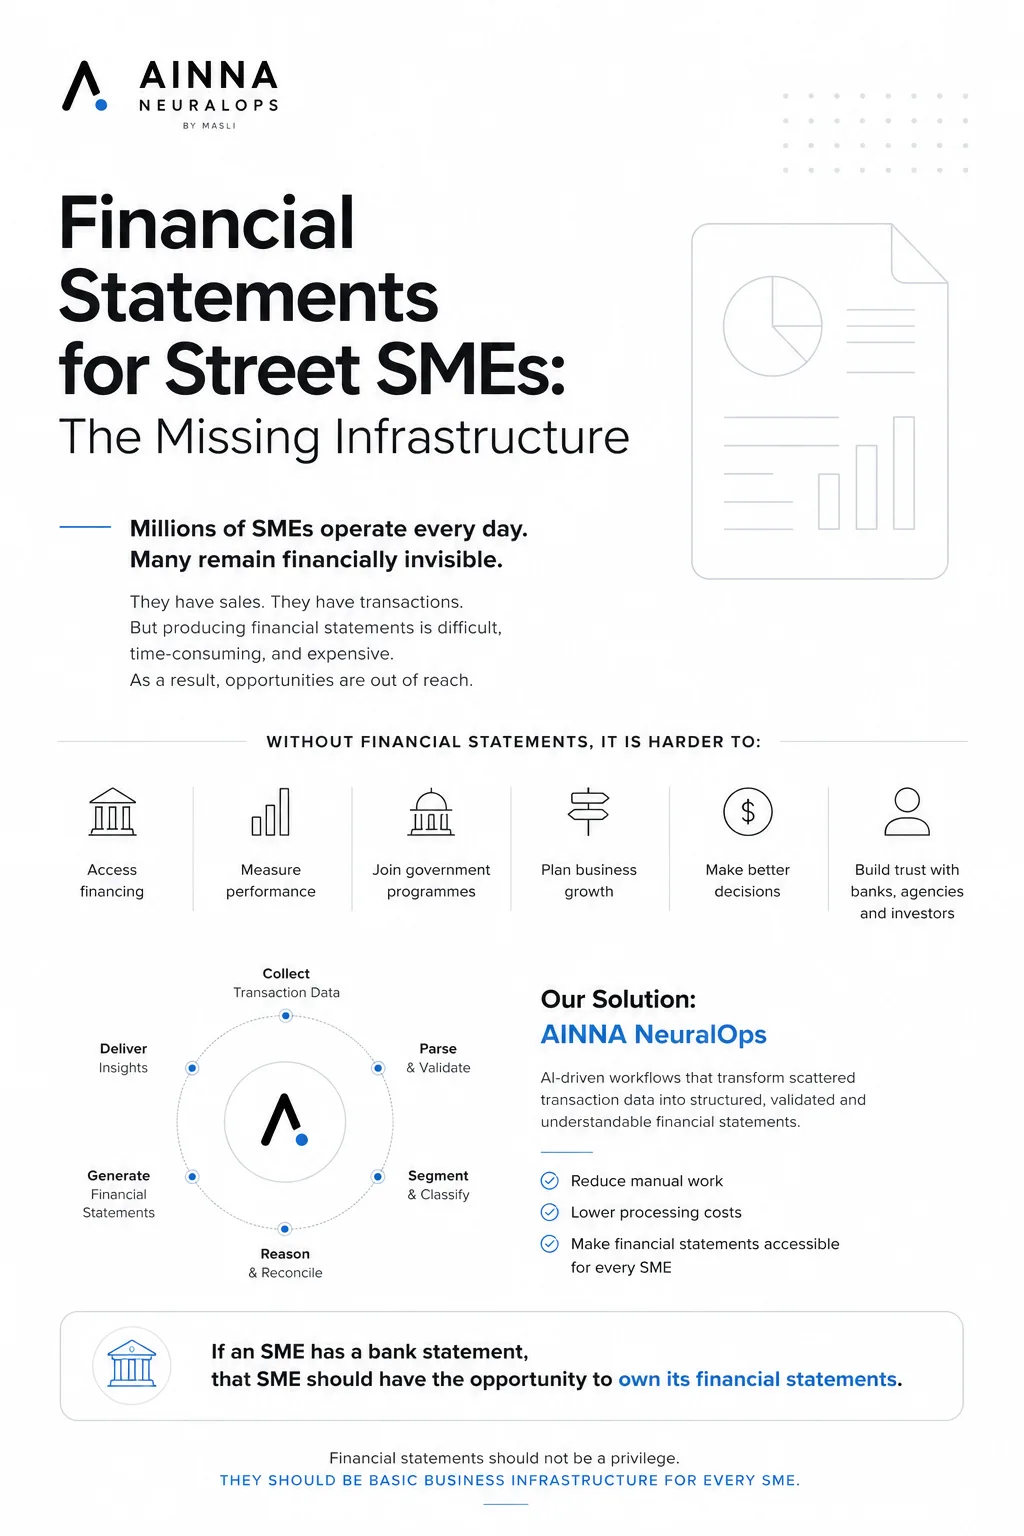
But many 中小企业 that have operated for years still have only one consistent financial record: their bank statements.
Debtor records may be incomplete. Creditor records may be missing. Fixed assets and inventory may never have been properly reconciled.
Accrual accounting is clearly the destination. But for 中小企业 rebuilding their accounts, cash records can be the most practical starting point.
One founder shared that during an LHDN audit, he was not penalised simply because his records were not yet fully accrual-based. Instead, some expenses were reassessed because of incorrect classification or tax treatment.
That distinction matters. 不完整 financial records are not the same as hiding income or avoiding tax.
A practical journey could be: 银行 Statement → 清理 现金 Ledger → 现金-Based 损益表 → Accrual Adjustments → 损益表 + 资产负债表. This is where AI and automation can help reconstruct financial data faster and more systematically.
My principle: 现金优先。权责发生制为最终目标。 合规 Throughout. 科技 should help 中小企业 start with what they already have and move progressively toward better financial reporting. #中小企业 #会计 #LHDN #AI #自动化 #财务报表 #马来西亚中小企业 #NeuralOps













Ruang pembaca
Apa pendapat anda?
Komen disemak sebelum diterbitkan. 电子邮件 diperlukan untuk moderasi dan tidak dipaparkan kepada pembaca.
难得有人把银行 statement讲得这么直白。
同意作者对fixed assets and inventory的判断,方向很清楚。
这篇文章把their bank statements讲得比一般的AI介绍更具体。
我喜欢文章对accrual-based保持务实的态度。
我特别喜欢accrual accounting这一部分,内容没有把实施过程说得太简单。
文章对i’ve spoken with several 中小企业提供了很好的起点,值得继续跟进。
我会把不完整 financial records这一段分享给需要了解技术的同事。
文章把cash records和日常运营联系起来,这一点很有帮助。