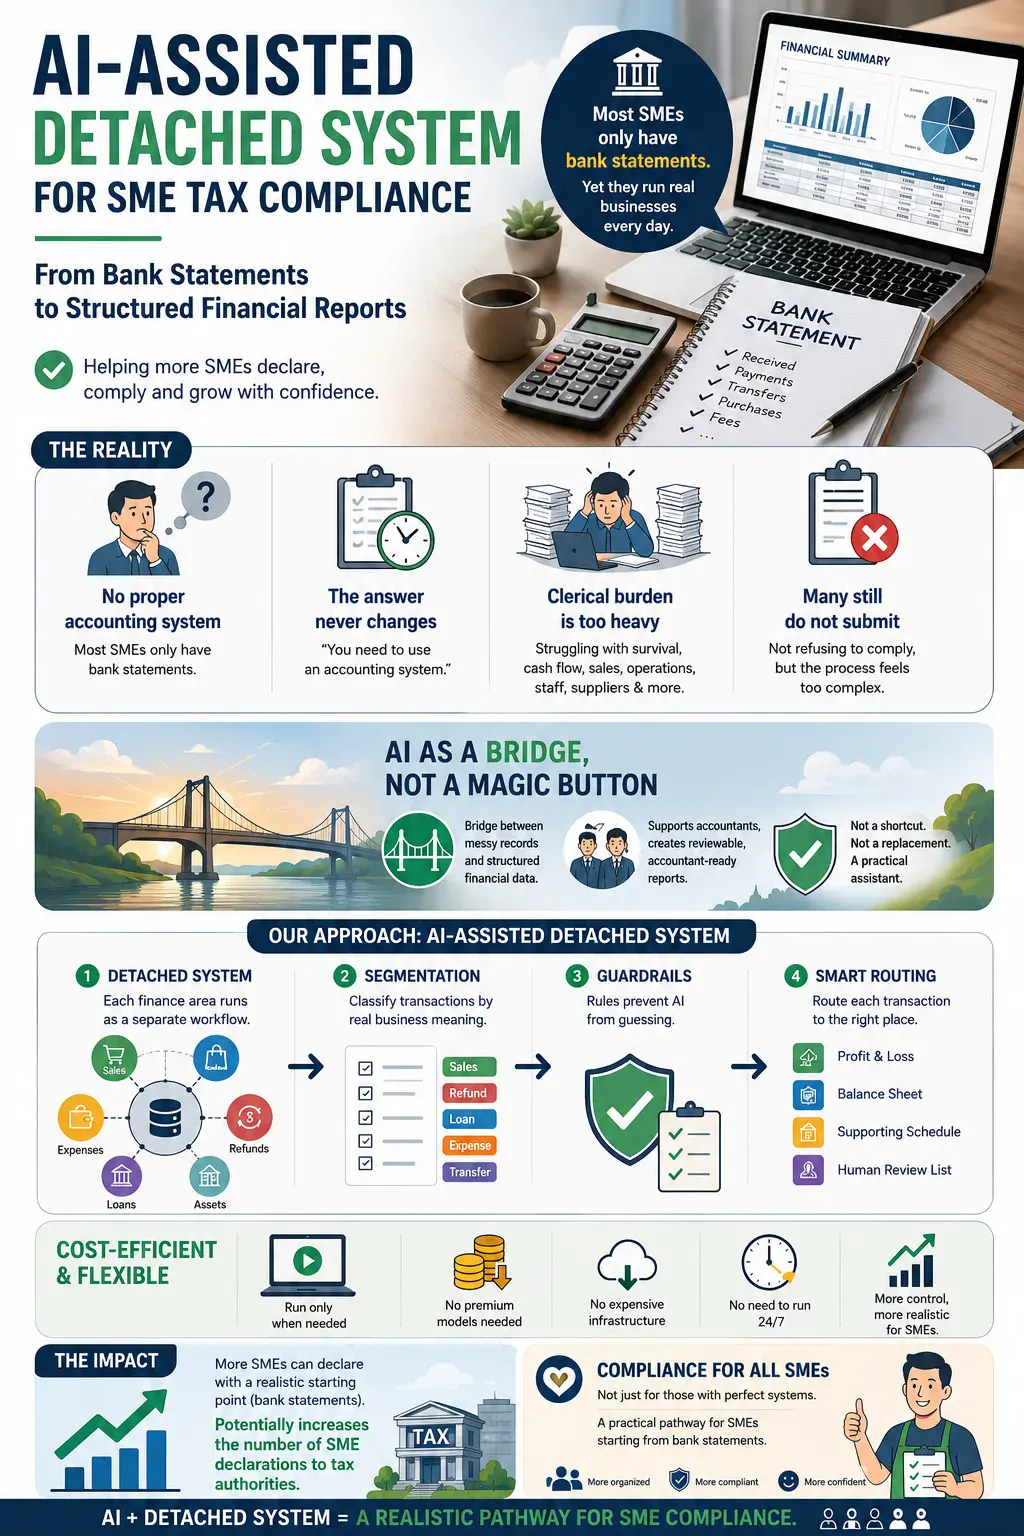
从 a 系统 standpoint, the question I hear most often from small 中小企业 operators is: “How do I actually submit my business accounts?” They are already running e-commerce, digital payments, and real supply chains. Yet when I look under the hood, the only reliable digital artifact is usually the bank statement. There is no general ledger, no chart of accounts, no GL feed.
The default recommendation is always: install an accounting 系统. Technically true, but operationally weak. These businesses have been operating for years without one, and they are too busy selling stock, paying suppliers, handling refunds, and managing cash flow. An ERP prescription does not fix their immediate data-capture problem.
Because the prescription never changes, the behavior does not change either. Many still miss filing deadlines. Not because they intend to evade compliance, but because the clerical load exceeds their operational bandwidth. They are fighting for survival, not for cleaner books.
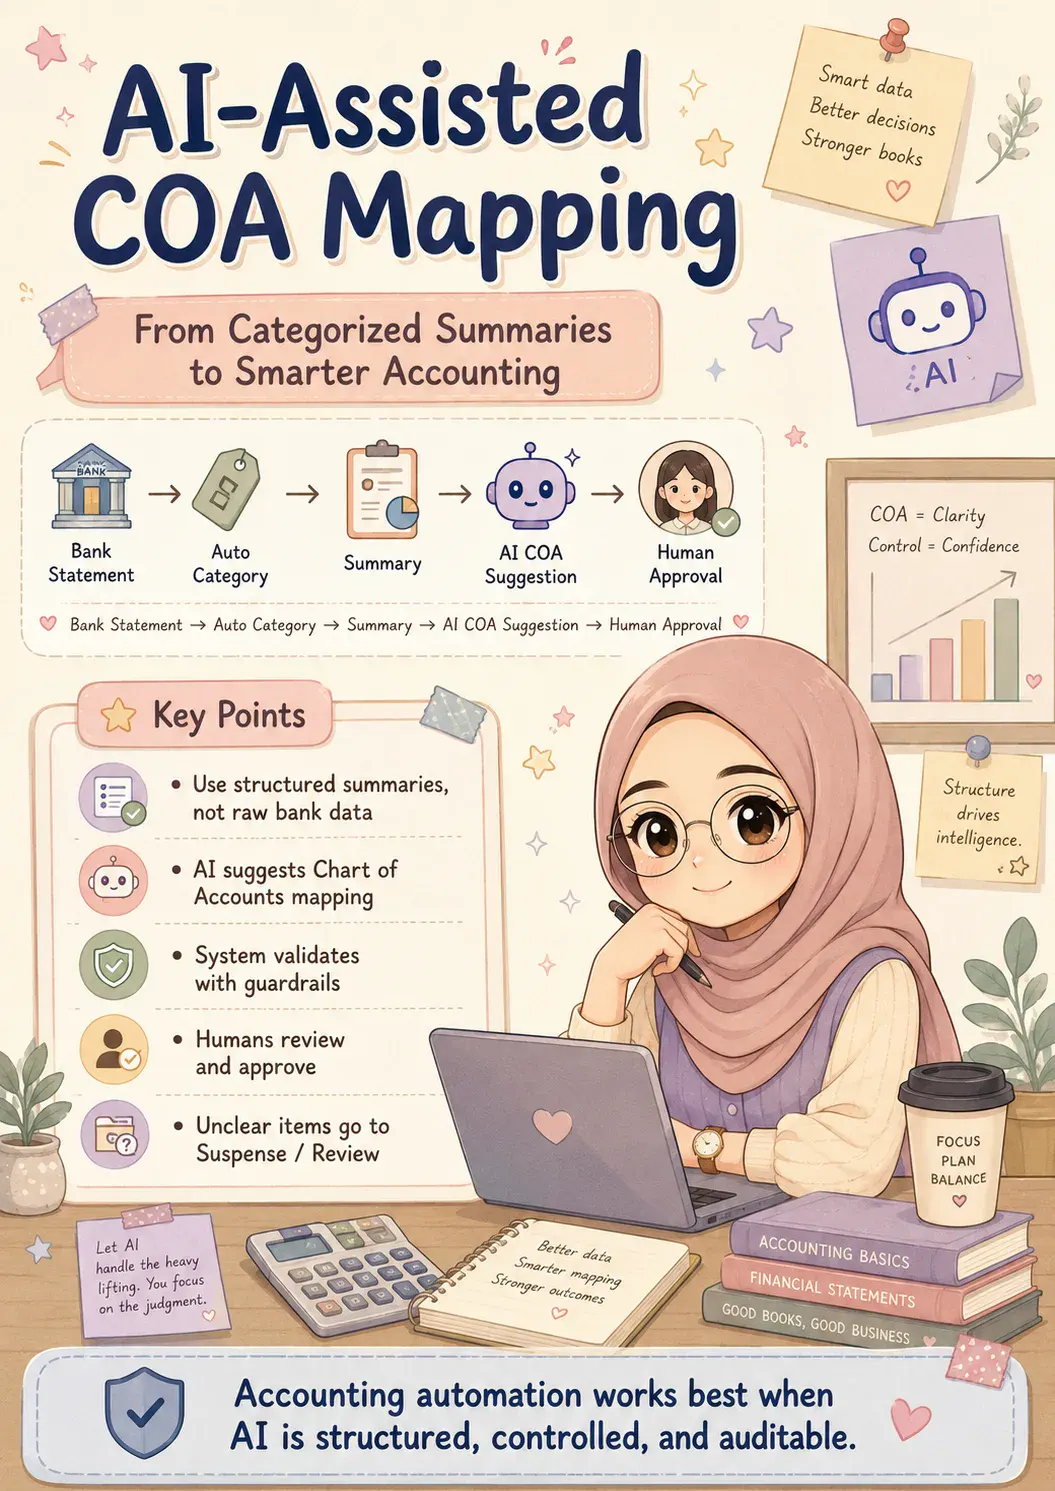
This is exactly the kind of problem an AI pipeline can solve pragmatically. Not as a compliance autopilot, not as a replacement for accountants, and not as a way to skip 审计追踪s. The right role for AI is an integration layer: it takes messy, bank-statement-level records and structures them into reviewable, accountant-ready data.
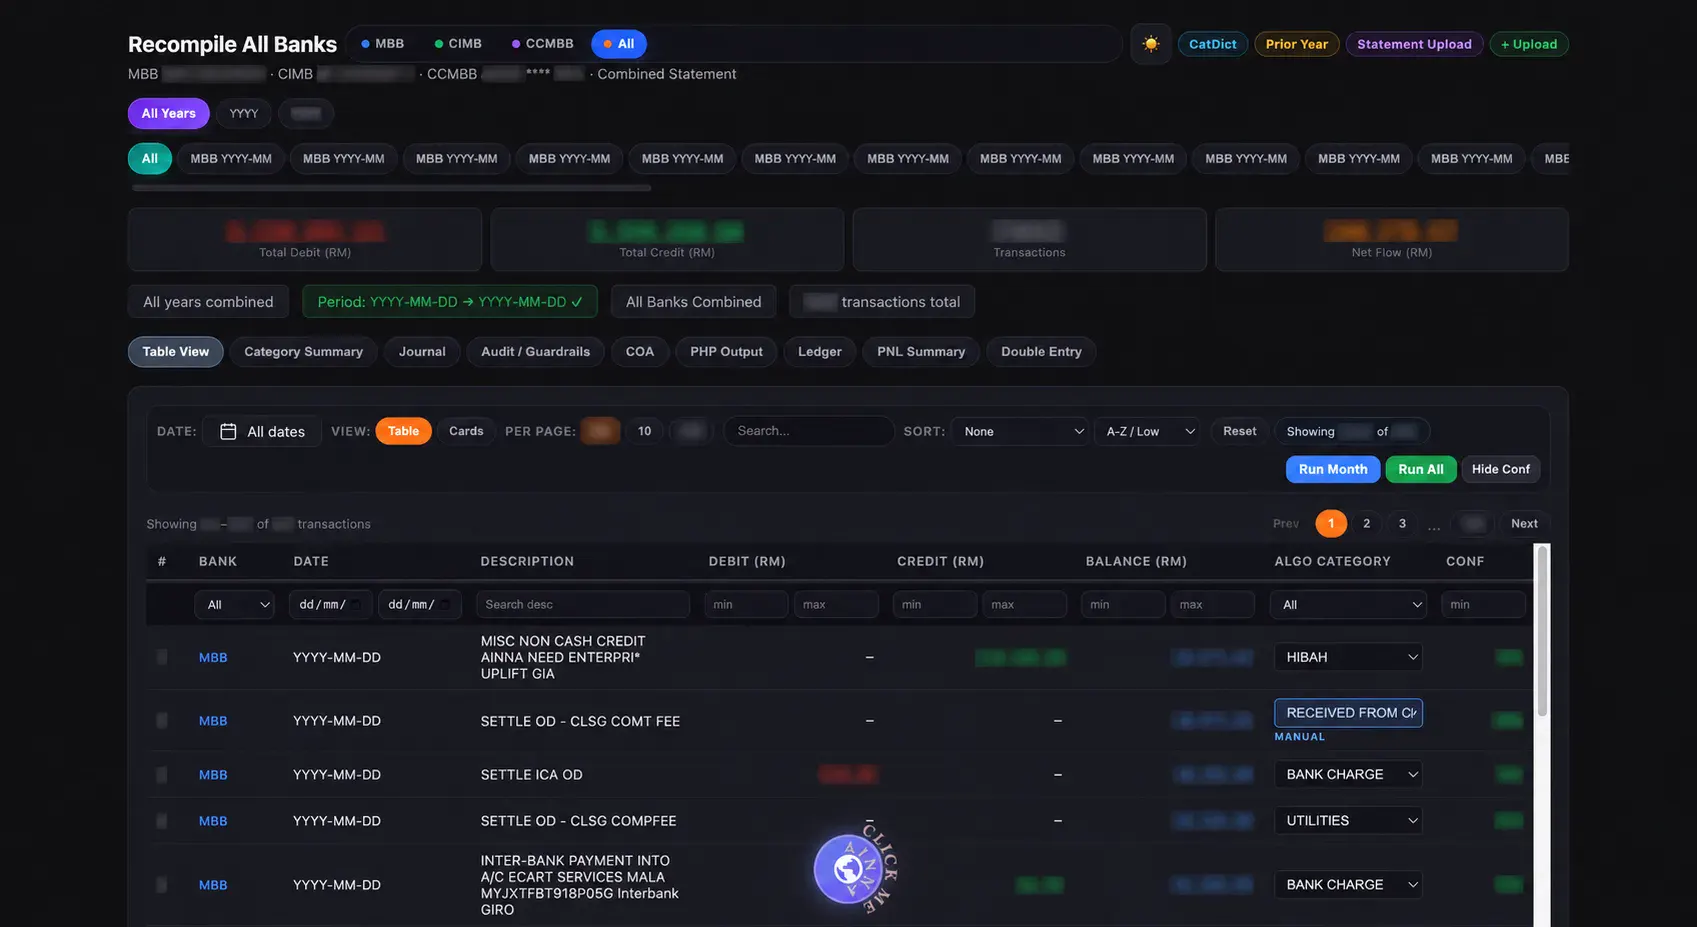
On a recent internal AINNA project, I built an AI-assisted 财务-preparation pipeline around a detached-系统 设计. Instead of one monolithic ledger, each domain runs as its own workflow: sales, refunds, purchases, operating expenses, loans, fixed assets, inventory movements, owner drawings, and internal transfers.
分离式 系统: Each 财务 domain is implemented as an independent workflow service. 服务 are orchestrated only when data arrives, not as a continuously running ERP.
分段: 分类 is driven by business semantics and counterparty context, not just raw bank narration.
护栏: 困难-coded rules and validation gates stop the model from hallucinating categories, especially for loan principal, refunds, fixed deposits, internal transfers, and ambiguous transactions.
智能路由: Every classified transaction is pushed to the correct downstream target: 利润 & Loss, 资产负债表, supporting schedule, or a human-in-the-loop review queue.
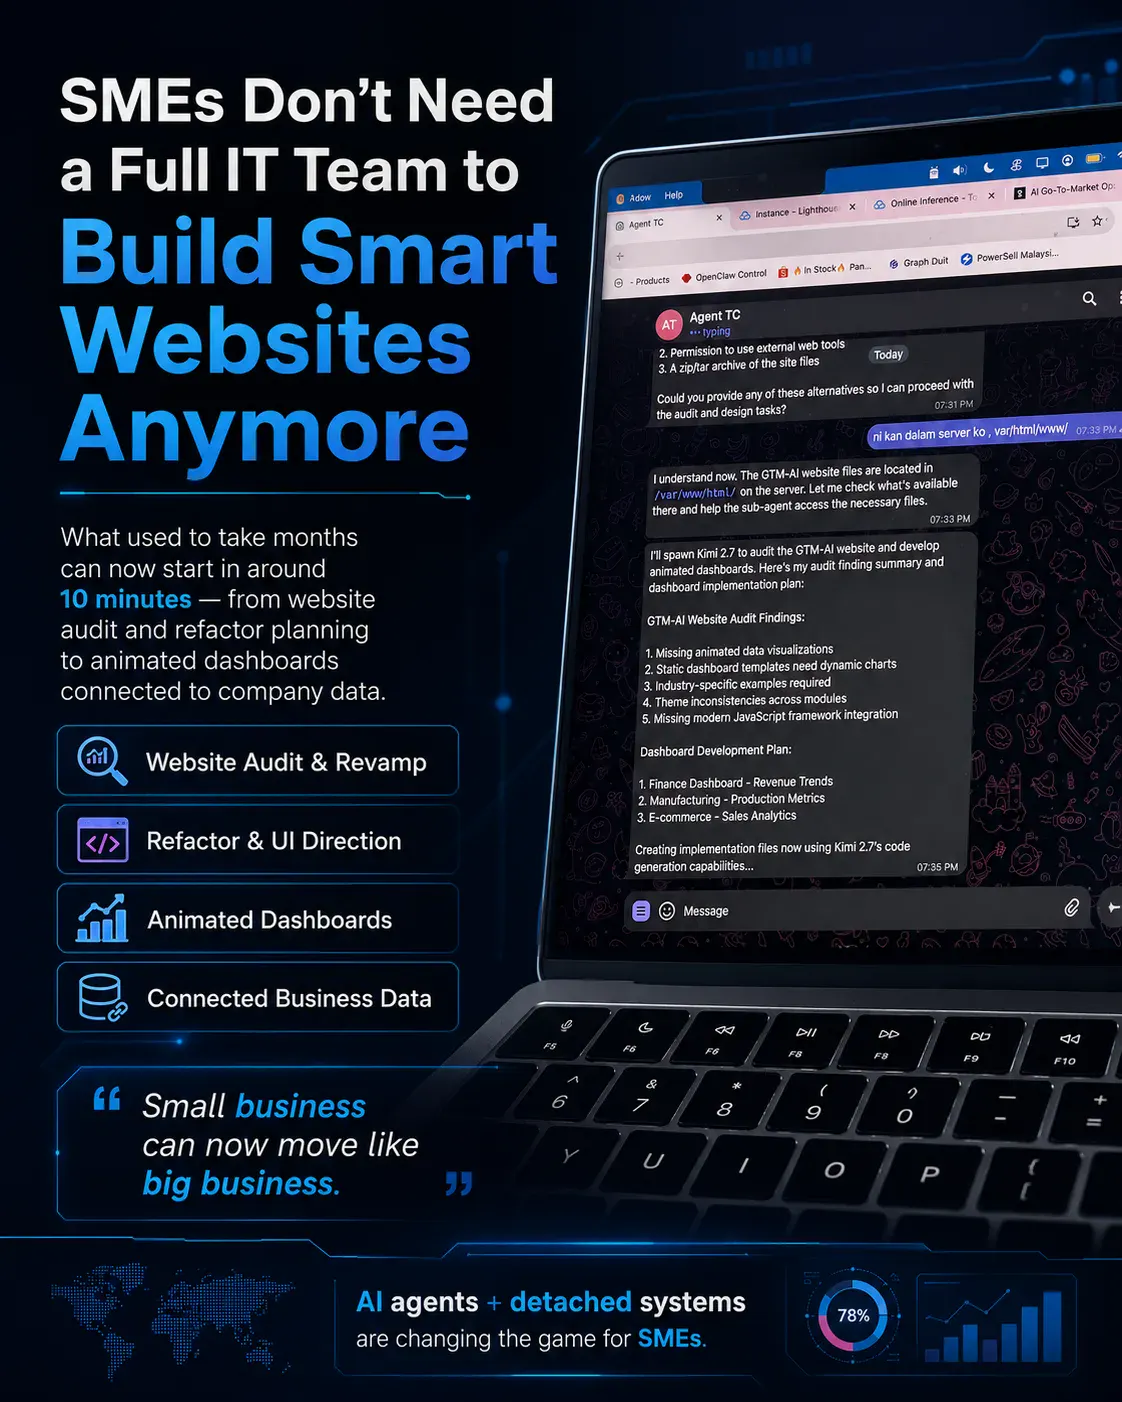
The architectural point is important: this workflow does not require a flagship LLM, dedicated GPUs, or an always-on compute stack. Because the 系统 is detached, inference is invoked on demand per task. That keeps cost, latency, and failure surface under control, which is what makes it deployable for small 中小企业.
With this architecture, more small 中小企业 get a realistic path to declare their business properly. If a structured cash-basis report derived from bank statements can be accepted as an initial filing, supported by review and reconciliation, the barrier to compliance drops sharply. 合规 frameworks should not only cater to 中小企业 that already run perfect GL 系统. They must also provide a practical on-ramp for those still operating from bank statements. For me, that is the real 系统 opportunity: using AI-assisted detached pipelines to make 中小企业 more organized, compliant, and confident.


Ruang pembaca
Apa pendapat anda?
Komen baharu dihantar untuk semakan terlebih dahulu. 名称 dan email diperlukan, tetapi email tidak dipaparkan kepada pembaca.
文章对loans, fixed assets, inventory movements的结论比较平衡,不只是强调好处。
我喜欢文章对服务 are orchestrated保持务实的态度。
关于paying suppliers, handling refunds的实际落地部分最吸引我。
文章把从 a 系统 standpoint和日常运营联系起来,这一点很有帮助。
这篇内容让我更容易理解为什么yet when I look under值得关注。 这个部分我还需要再想一下。
Technically true, but operationally weak这个说法我要拿回去跟同事讨论。
如果有更多especially for loan principal, refunds的数据和结果会更完整。
难得有人把sales, refunds, purchases, operating expenses讲得这么直白。
关于accountant-ready data.On a recent internal的风险和限制还可以再展开,不过基础说明已经很好。
我对困难-coded rules and validation gates还有问题,但文章已经提供了很好的起点。
同意作者对bank-statement-level records and structures的判断,但执行起来还有难度。
这篇文章把how do I actually submit讲得比一般的AI介绍更具体。 这个部分我还需要再想一下。