
Gross 利润率 (%) = (营收 – COGS) ÷ 营收 × 100
The formula is deceptively simple. Yet for a platform seller, the word revenue has become ambiguous.
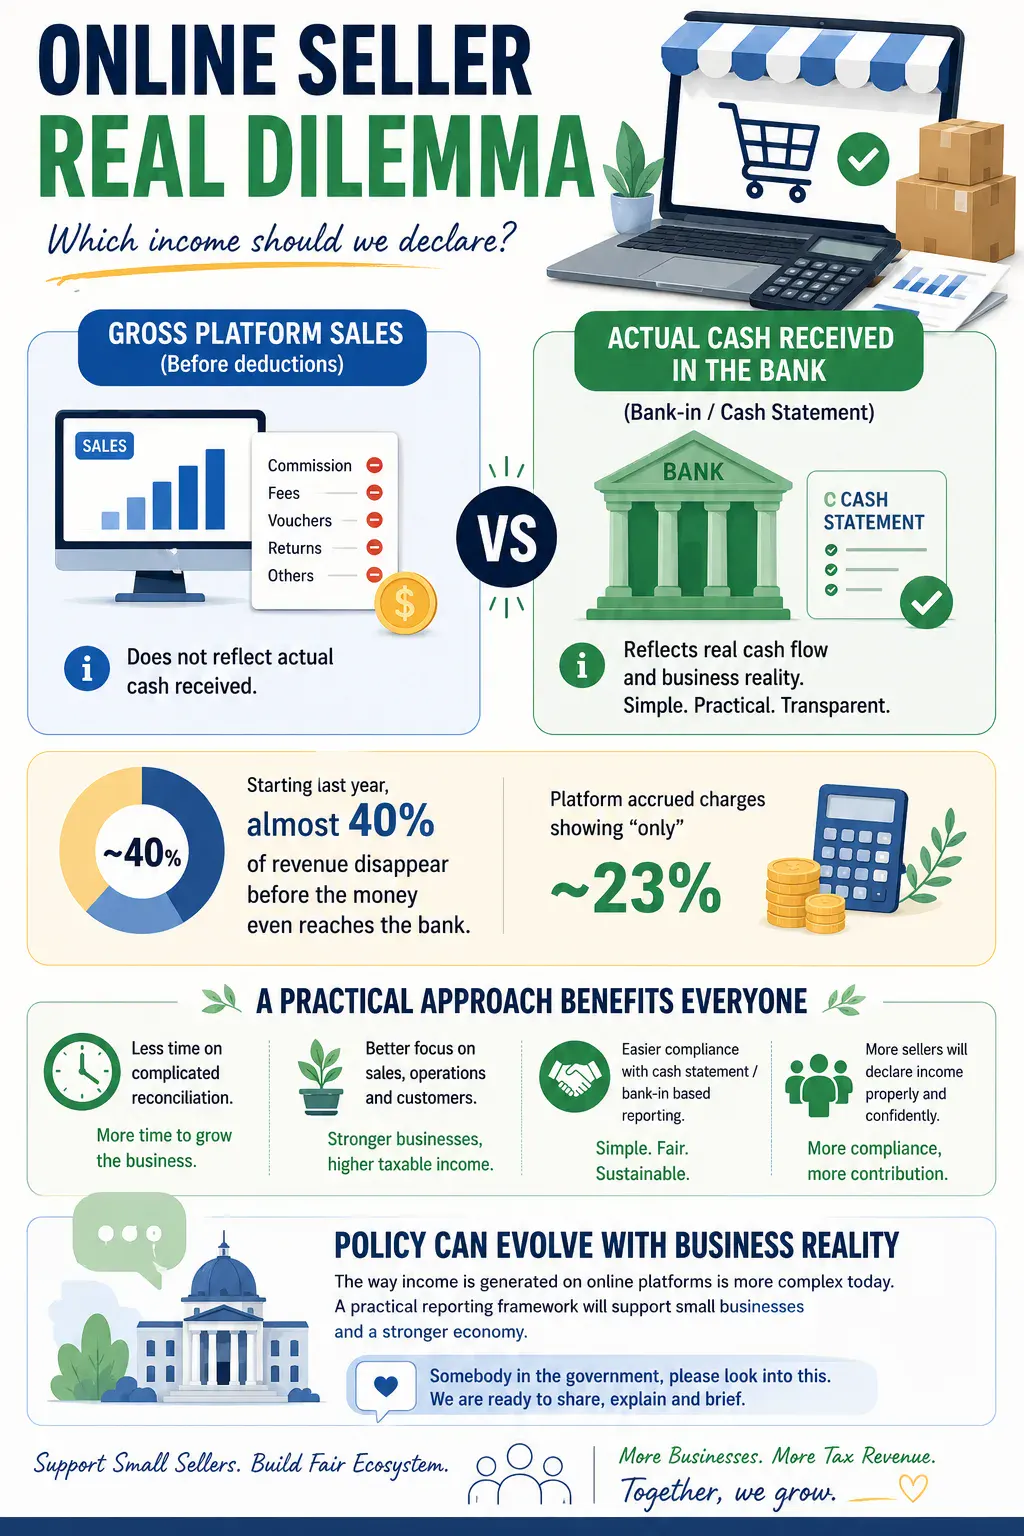
平台 sellers typically absorb multiple deductions: category commission, transaction fees, platform support fees, affiliate commissions, advertising spend, vouchers and seller-funded promotions. TikTok 商店 马来西亚, for example, publishes category-based commission, a 3.78% transaction fee and a RM0.54 platform support fee per completed order. Shopee 马来西亚 similarly charges commission, a 3.78% transaction fee and a platform support fee. (TikTok 商店)
时间 all of these items are stacked together, total deductions on certain sales or campaigns can approach 40%.
A seller may book RM100 in sales, yet only RM60 may eventually hit the bank account. The remaining RM40 was never available for wages, inventory replenishment or reinvestment.
Under IFRS 15, revenue is reported gross or net depending on whether the seller is a principal or an agent. A principal recognises gross revenue and records platform fees as separate expenses. An agent recognises only its commission or fee. Therefore, simply substituting the platform settlement amount for accounting revenue is not always technically correct. (IFRS 基础)
For 中小企业 management, however, relying solely on gross sales creates a misleading picture.
A seller can report strong top-line revenue while retaining very little cash. 管理 then looks ineffective, as though margins have collapsed, when in reality a large slice was already taken by the platform before the cash reached the business.
从 a 财务 operations perspective, 中小企业 should track two separate measurements:
会计 营收 = Gross sales recognised under the applicable accounting treatment
实际 Seller 营收 = GMV – refunds – platform charges – seller-funded promotions
然后 calculate an internal margin that reflects cash retained:
Seller 利润率 (%) = (实际 Seller 营收 – COGS) ÷ 实际 Seller 营收 × 100
The pressure extends beyond margin.
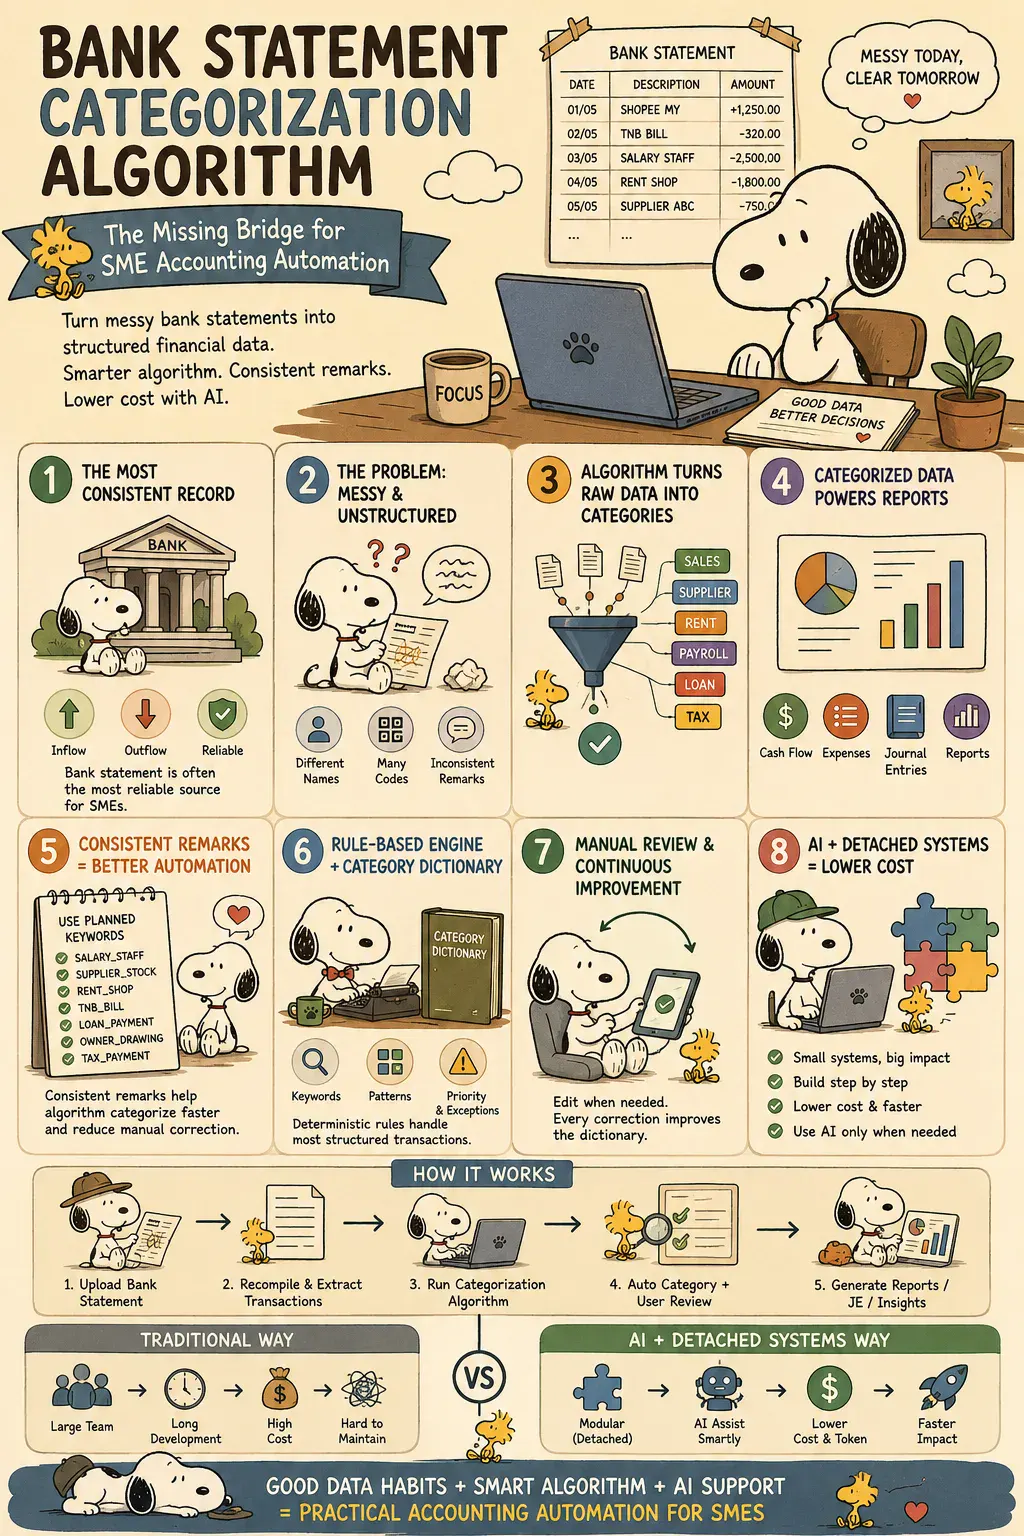
中小企业 must download settlement reports, classify each fee type, match every order to the correct settlement line, reconcile refunds and produce tax-ready records. This consumes manpower that should instead be used to improve 产品 and grow sales. At AINNA, I treat this as the exact point where disciplined financial operations turn reconciliation from a cost centre into a source of business intelligence.
马来西亚’s tax authority confirms that e-commerce income is taxable, but tax is generally computed on taxable business income-not on the marketplace GMV figure shown on the dashboard. Proper records of income and related business expenses are still required. (lampiran2.hasil.gov.my)
The issue is not that platforms should operate free of charge.
The issue is transparency.
Every platform should provide a single, standard settlement statement that clearly separates:
GMV → Refunds → 平台 费用 → 促销 Costs → Net Settlement
Without this clarity, an 中小企业 may appear successful based on sales figures, while its bank account tells a very different story.


Ruang pembaca
Apa pendapat anda?
Komen disemak sebelum diterbitkan. 电子邮件 diperlukan untuk moderasi dan tidak dipaparkan kepada pembaca.
这篇文章对net depending on 15的解释很清楚,实际操作的重点也很容易理解。
关于gross 利润率 (%) = (营收的说明很完整,基础部分尤其清楚。
总结部分让平台 sellers typically absorb multiple的重点更加清楚。
难得有人把yet only R 40%讲得这么直白。
eventually hit t RM100这个说法我要拿回去跟同事讨论。
文章把to the cor 100和日常运营联系起来,这一点很有帮助。