In the last few field deployments I’ve worked with 中小企业 founders, the same gap keeps surfacing: 损益表, 资产负债表, and LHDN readiness. Most agree their financial reporting stack needs to be rebuilt.
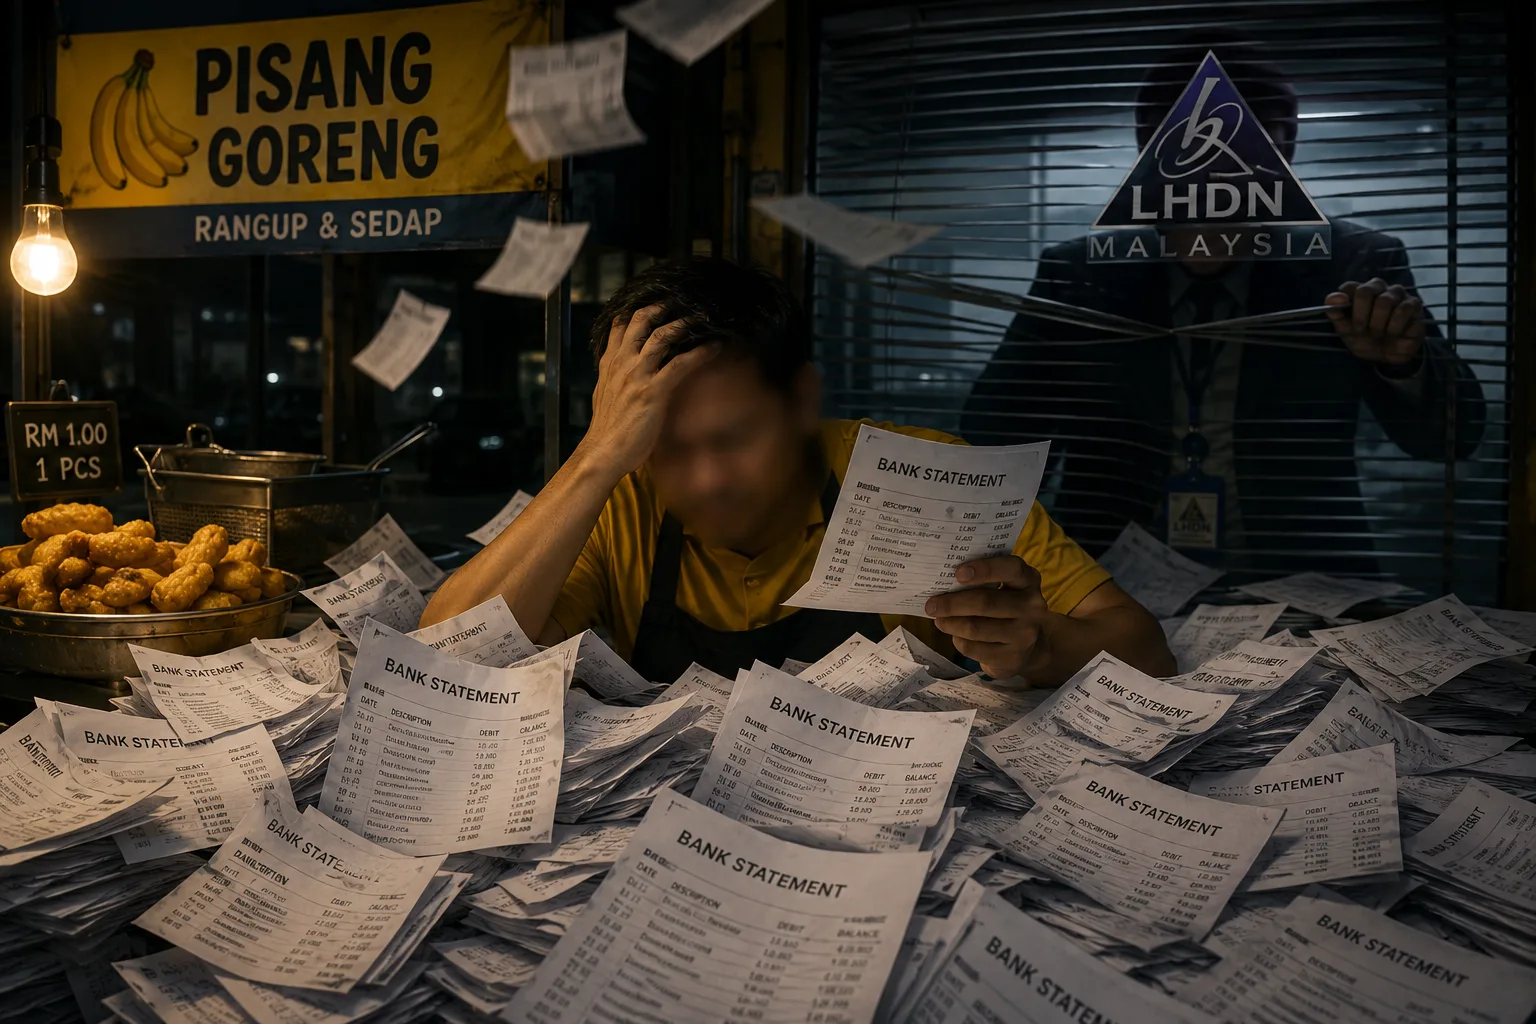
But after years of operations, many 中小企业 still have only one reliable source of truth: their bank statements.
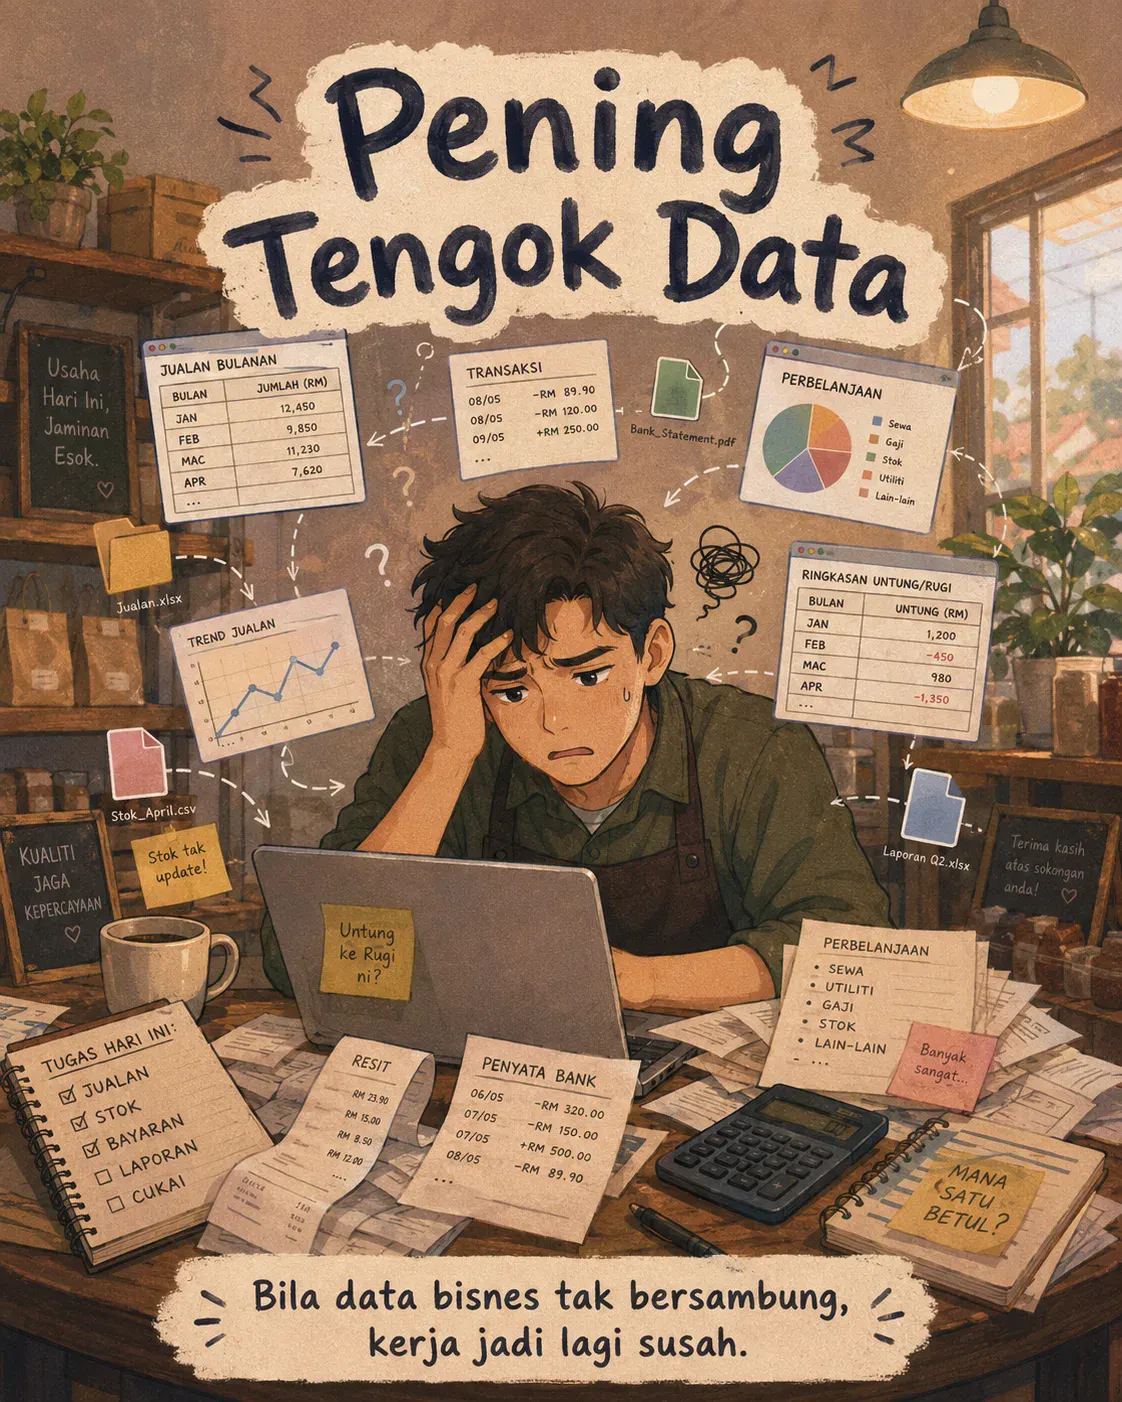
Debtor records are often incomplete. Creditor records may not exist. Fixed assets and inventory are rarely reconciled properly. The auxiliary data 层 are broken.
Accrual accounting is the target architecture. But when you’re rebuilding the ledger from scratch, cash records are the most practical entry point.
One founder told me that during an LHDN audit, he was not penalised just because his records were still cash-based. The issue was expenses being reassessed due to wrong classification or tax treatment.
That distinction is critical. 不完整 records are not the same as concealment or tax evasion.
A practical pipeline is: 银行 Statement → 清理 现金 Ledger → 现金-Based 损益表 → Accrual Adjustments → 损益表 + 资产负债表. This is where AI and automation come in - to ingest, classify, reconcile, and rebuild the financial data layer faster and more systematically.
My operating principle: 现金优先。权责发生制为最终目标。 合规 by 设计. The right 系统 architecture lets 中小企业 start with existing data and progressively upgrade their financial reporting layer. #中小企业 #会计 #LHDN #AI #自动化 #财务报表 #马来西亚中小企业 #NeuralOps


Ruang pembaca
Apa pendapat anda?
Komen disemak sebelum diterbitkan. 电子邮件 diperlukan untuk moderasi dan tidak dipaparkan kepada pembaca.
如果可以继续说明银行 statement的真实案例,我会想继续阅读。
这篇文章对cash records的解释很清楚,实际操作的重点也很容易理解。
关于不完整 records的实际落地部分最吸引我。
文章对cash-based的结论比较平衡,不只是强调好处。
我特别喜欢fixed assets and inventory这一部分,内容没有把实施过程说得太简单。