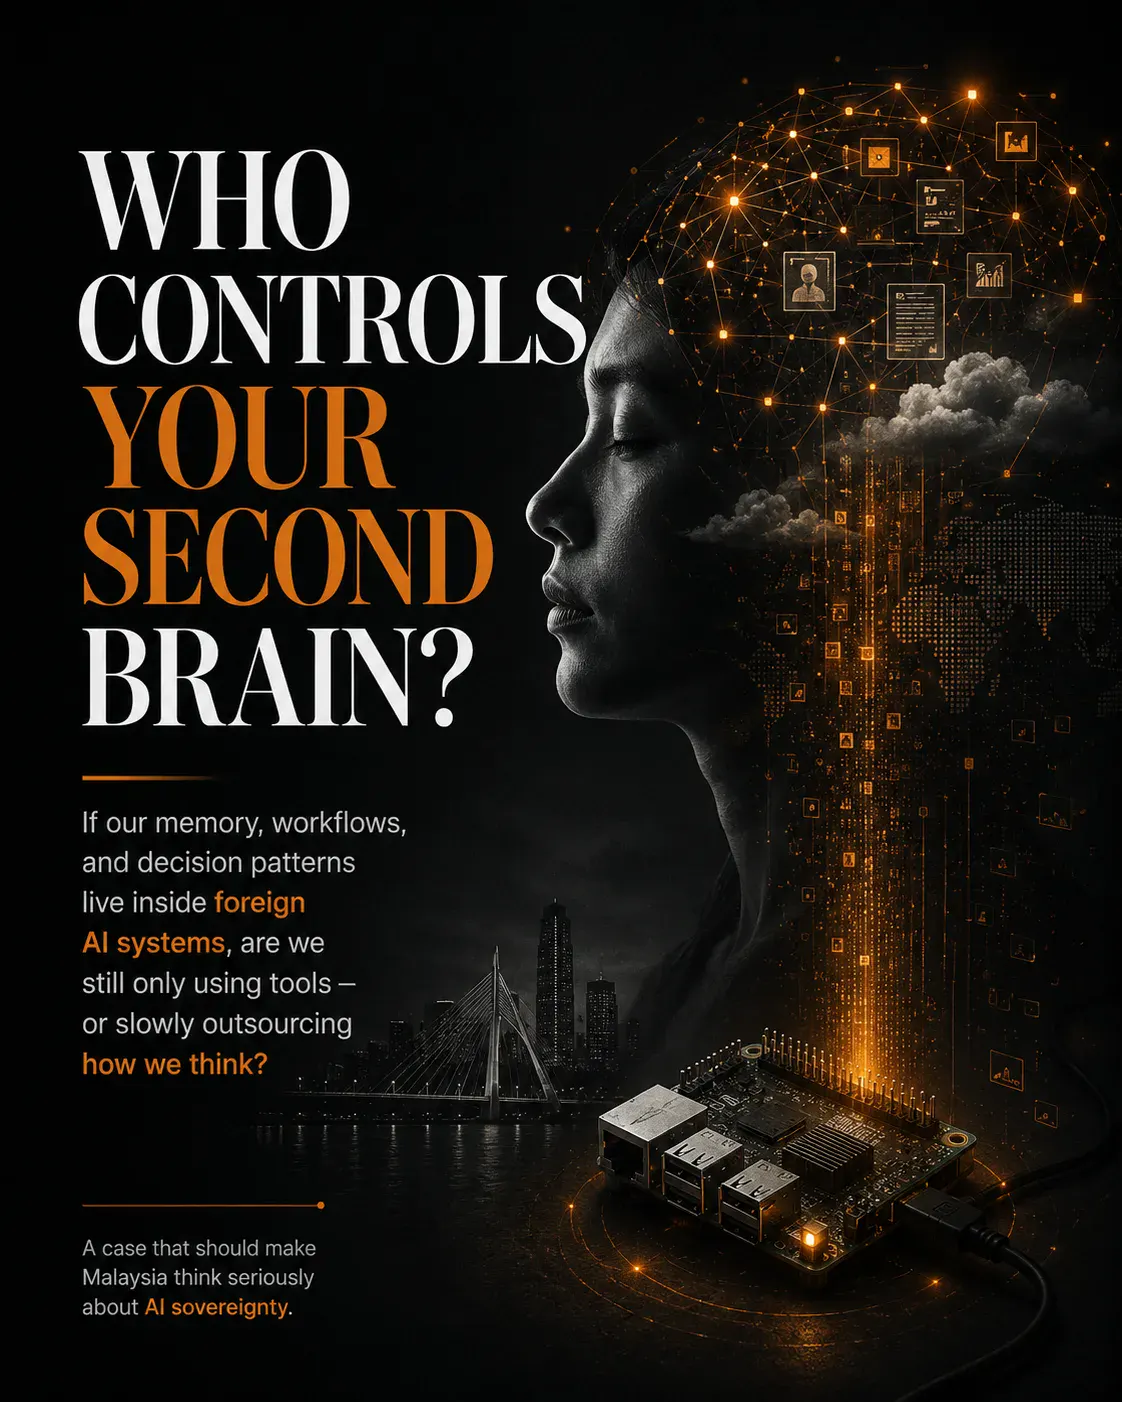
从 a 财务 and accounting standpoint, this is not just a technology headline; it is a case study in asset control and vendor concentration risk. If a senior decision-maker can own the device, the model, the data trail, and the memory layer, the implication 面向马来西亚中小企业 is clear: AI 能力 can be treated as an internally controlled asset, or as a recurring, opaque operating expense with governance exposure.
For 财务 leaders, AI is not simply a productivity tool. It is an intangible asset class sitting at the edge of every decision: customer records, 预测ing logic, pricing behaviour, supplier terms, and management judgement patterns. The question is not whether we use AI, but whether that knowledge remains on our balance sheet or becomes embedded in a third-party provider’s training signal.
Over-reliance on foreign AI models creates more than data-leakage risk. It creates concentration risk. Every prompt, query, and workflow we feed into an external model is a transfer of operational intelligence: how we approve budgets, manage inventory, price 产品, assess debtors, and make capital calls. Over time, the provider gains visibility into our decision-making rhythm before our own internal controls have documented it.
In accounting terms, every prompt is a transaction. It records intent, timing, priority, and context. 时间 those transactions sit outside our audit perimeter, we lose the ability to fully verify provenance, assure confidentiality, or support statutory reporting. That is not a technology inconvenience; it is a control weakness that auditors and regulators will eventually price in.
马来西亚n businesses should not abandon foreign models. They are cost-effective, fast to deploy, and useful for general research, coding, and low-sensitivity tasks. But they belong in the right cost centre, with clear usage policies, data classification rules, and segregation of duties.
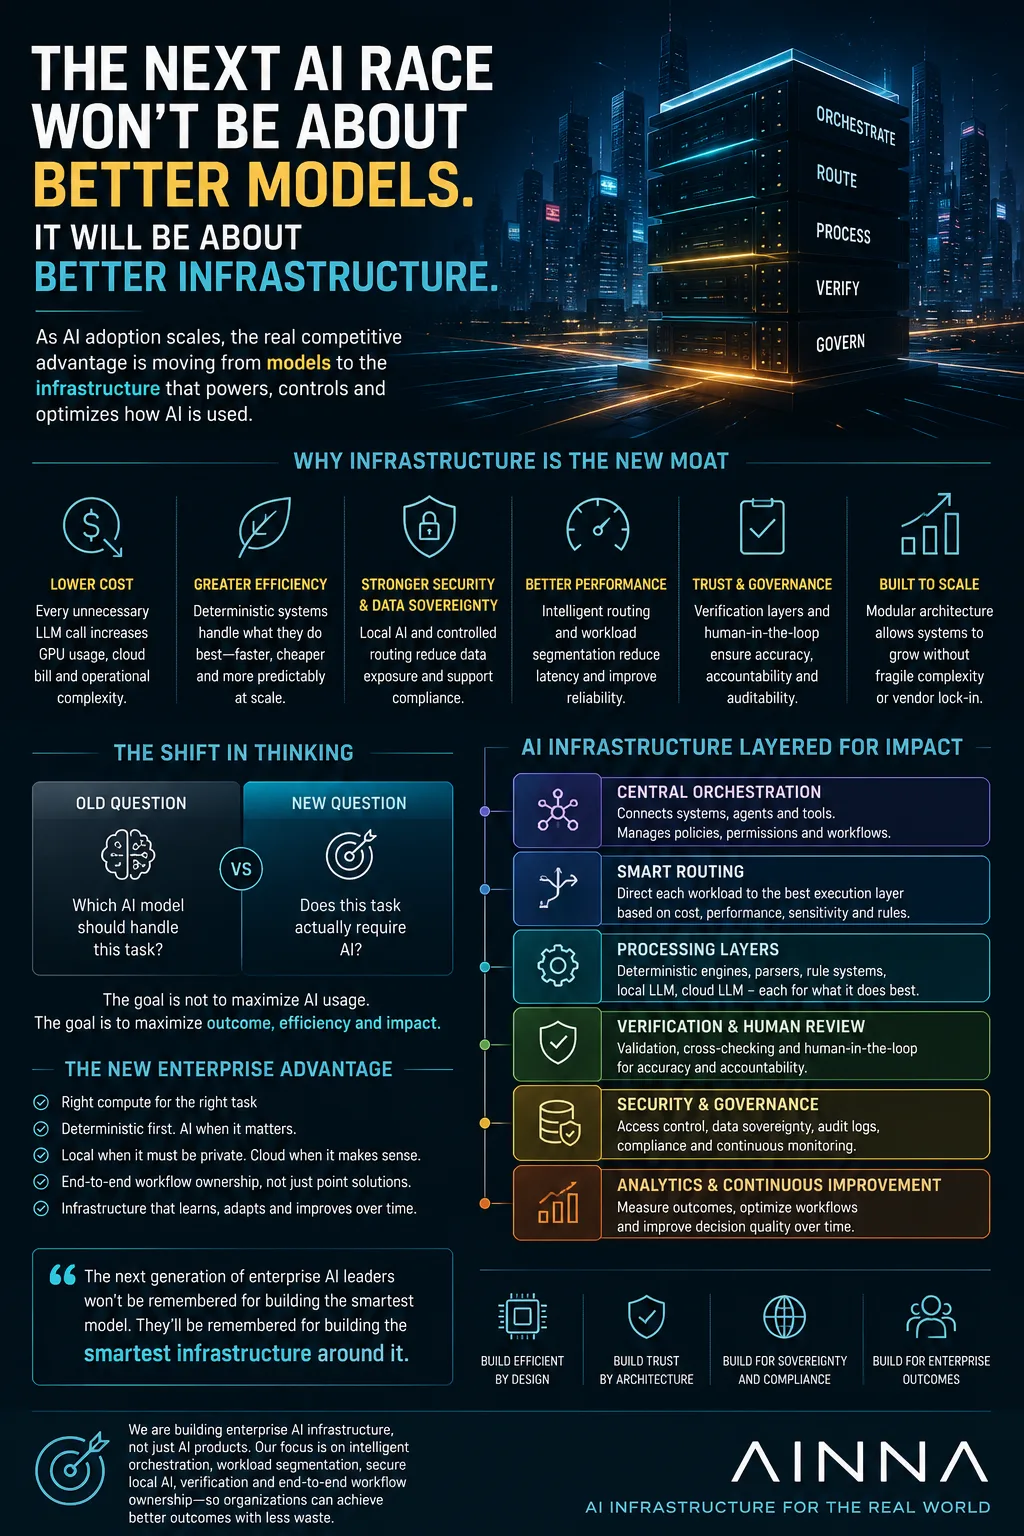
从 an asset-management perspective, we need a hybrid AI operating model: foreign models for speed and scale, local or private models for sensitive data, on-premise or sovereign infrastructure for regulated workloads, and internal capability to capitalise knowledge assets rather than continuously rent them. At AINNA, we work with 马来西亚n 中小企业 to put that control layer in place, so AI investments map to measurable business value rather than recurring vendor lock-in.
The real question is not whether we adopt AI. It is whether we are building an AI 能力 we can account for, secure, and govern. If a minister can run a second brain from his desk, every 中小企业 board should be asking: who owns ours, where is the data capitalised, and what happens if the subscription stops?
主权ty in this context is not abstract. It is an accounting and operational discipline: data ownership, model control, infrastructure choice, audit rights, and decision authority. For 马来西亚n 中小企业, getting this right is the difference between AI as a controlled asset and AI as an unrecorded liability.
#AI主权ty #主权AI #马来西亚AI #LLM #Artificial智能 #数据主权ty #数字化主权ty #AI基础设施 #LocalAI #AI战略
Official 跨-网络 Resource













Ruang pembaca
Apa pendapat anda?
Komen disemak sebelum diterbitkan. 电子邮件 diperlukan untuk moderasi dan tidak dipaparkan kepada pembaca.
这篇文章把已关联 to claude讲得比一般的AI介绍更具体。
总结部分让时间 those transactions sit outside的重点更加清楚。
如果还有这篇文章的后续,我会继续读。
这个主题这部分我看了几遍,值得再想。
这篇文章适合团队用来开始讨论从 a 财务 and accounting。