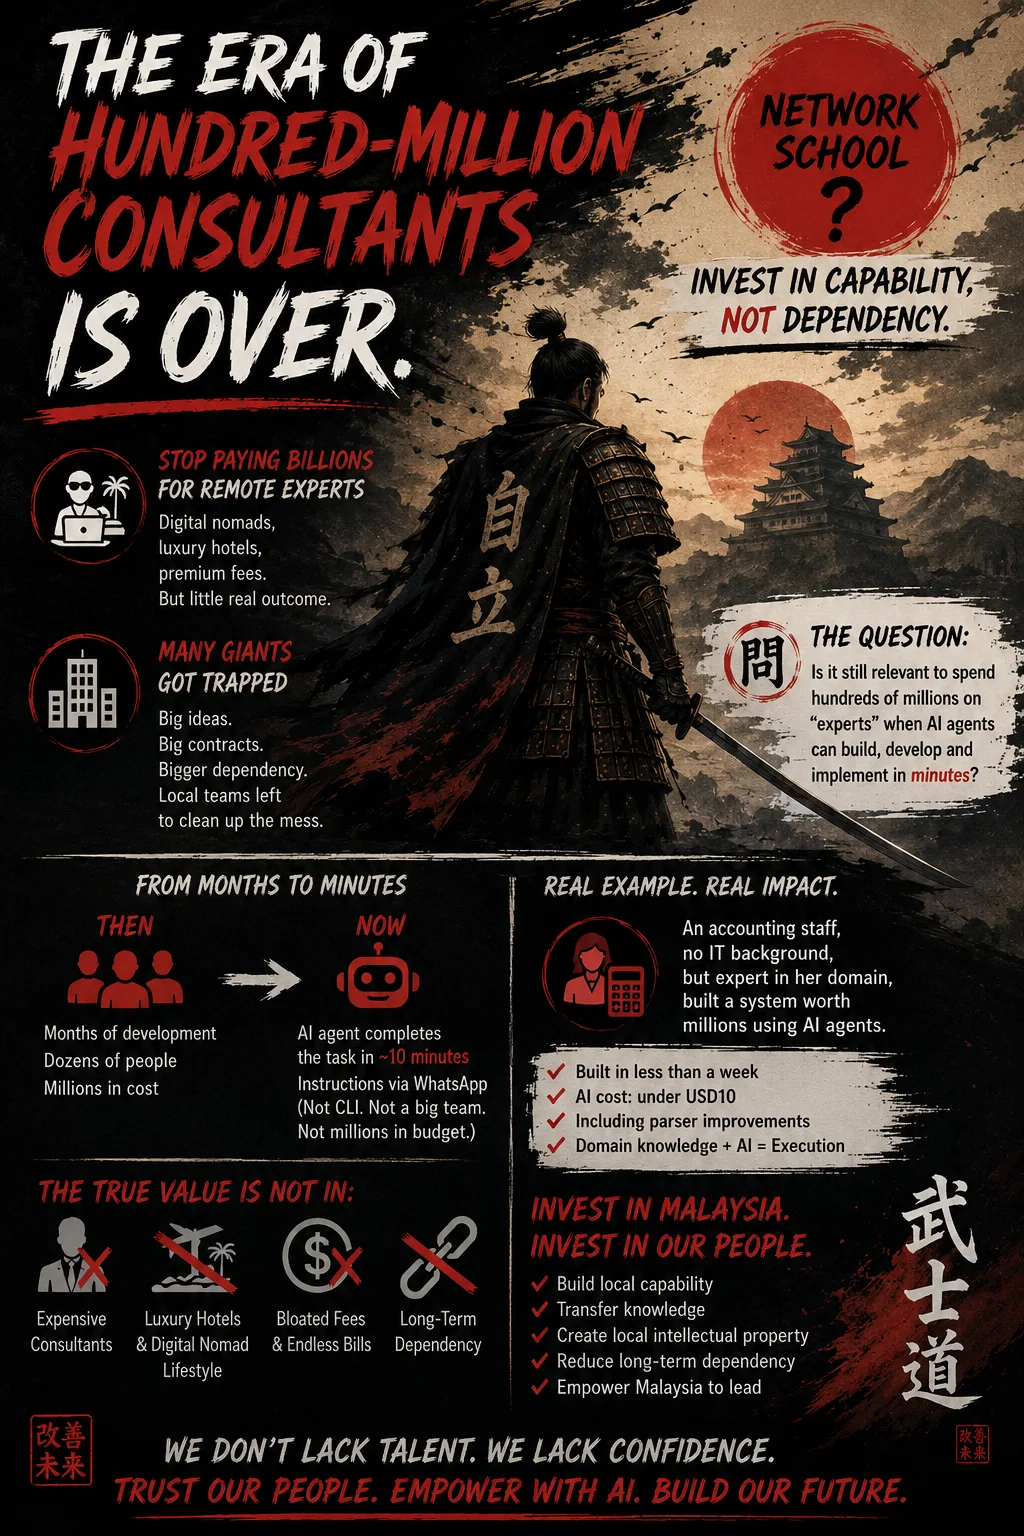
从 a 财务 and accounting standpoint, I am still trying to determine how 网络 School's reported nine-figure commitment should be classified on the books. Is it capital expenditure, a long-term services contract, or a transfer payment that never converts into a 马来西亚n-owned asset?
I hope it is not a repeat of a familiar procurement pattern: technology concepts valued in the hundreds of millions, foreign "specialists" positioned as the only qualified implementer, and large 马来西亚n 企业s locked into multi-year engagements covering advisory, development, support, and licensing. The lifetime cost often runs into billions, while the intellectual property and operational know-how remain offshore.
Some of those concepts were sound.
The execution and the economics were not.
The historical model saw senior consultants operating from beachside locations and luxury hotels, billing premium rates while local engineers were left to integrate, troubleshoot, and sustain the 系统 on the ground. 时间 those engagements stalled or became unmanageable, it was local teams that absorbed the cost and effort of rebuilding and stabilising them.
In many cases, the rescue work was done by 马来西亚n talent using resources that had already been paid for twice: once to the original vendor, and again to fix the outcome.
I am not commenting on politics or geopolitics.
My concern is capital allocation and asset ownership.
If 网络 School's investment is directed at digital platforms, software, or innovation, then 财务 leaders should ask a straightforward question:
Is it still financially rational to commit hundreds of millions to imported "world-class" digital consultants when AI 智能体 can now produce comparable ideas, prototypes, and working implementations in minutes?
I am speaking from the 财务 and accounting operations side at AINNA, where every ringgit must be traceable to either a balance-sheet asset or a measurable operational outcome for the 中小企业 we support.
Previously, a single software build could consume months of budget and dozens of full-time equivalents.
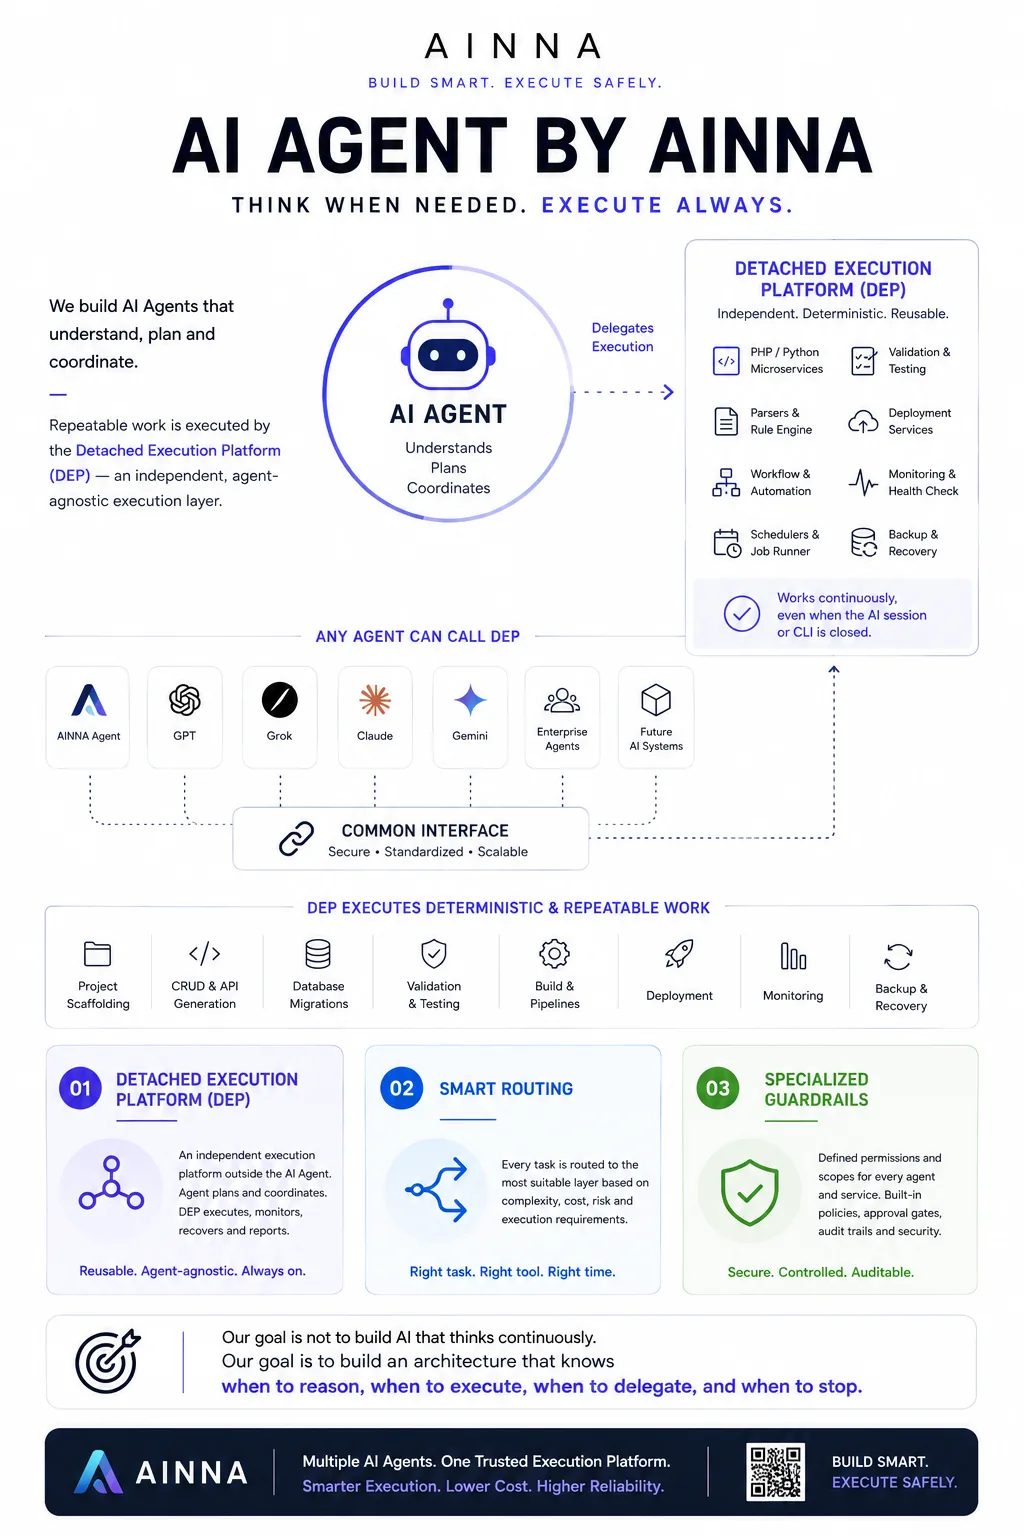
今天, an AI agent can complete specific development tasks in roughly 10 minutes while I issue instructions through WhatsApp-without touching a 命令行. The cost is a fraction of one hour of traditional consulting.
Here is a concrete example from our own operations.
One of our accounting staff has no formal IT training. She is, however, an expert in accounting operations.
By combining her domain knowledge with AI 智能体, she designed and deployed a 系统 that a traditional consulting firm could have priced in the millions of ringgit.
The full implementation, including several parser refinements, was finished in under a week at an AI cost of below USD10.
That is the financial shift 财务 teams at 马来西亚n 中小企业 need to understand.
The competitive advantage is no longer about procuring the most expensive advisory brand.
It belongs to organisations that understand their own 工作流, equip their domain experts with AI, and deliver results quickly.
马来西亚n 中小企业 do not lack talent.
What they often lack is budgetary confidence in their own people.
Sound investment should create 马来西亚n-owned intangible assets, transfer operational knowledge, and reduce long-term vendor dependency. For the 中小企业 AINNA works with, that translates into improved gross margin, lower support cost, or faster close cycles-not a recurring drain on the 损益表.
It should not create another generation of expensive reliance on external consultants.
Perhaps the question is no longer whether 马来西亚 can build world-class technology.
The real question is whether our 财务 leaders still believe we need to rent that capability from abroad instead of growing it on our own balance sheet.













Ruang pembaca
Apa pendapat anda?
Komen disemak sebelum diterbitkan. 电子邮件 diperlukan untuk moderasi dan tidak dipaparkan kepada pembaca.
视觉和结构让where every ringgit的概念更容易掌握。
文章把the competitive adv 10和日常运营联系起来,这一点很有帮助。
看第二遍才注意到technology concepts valued的细节。
我特别喜欢时间 those engagements stalled这一部分,内容没有把实施过程说得太简单。
这篇文章对once to the original vendor的解释很清楚,实际操作的重点也很容易理解。
如果可以继续说明touching a 命 10的真实案例,我会想继续阅读。