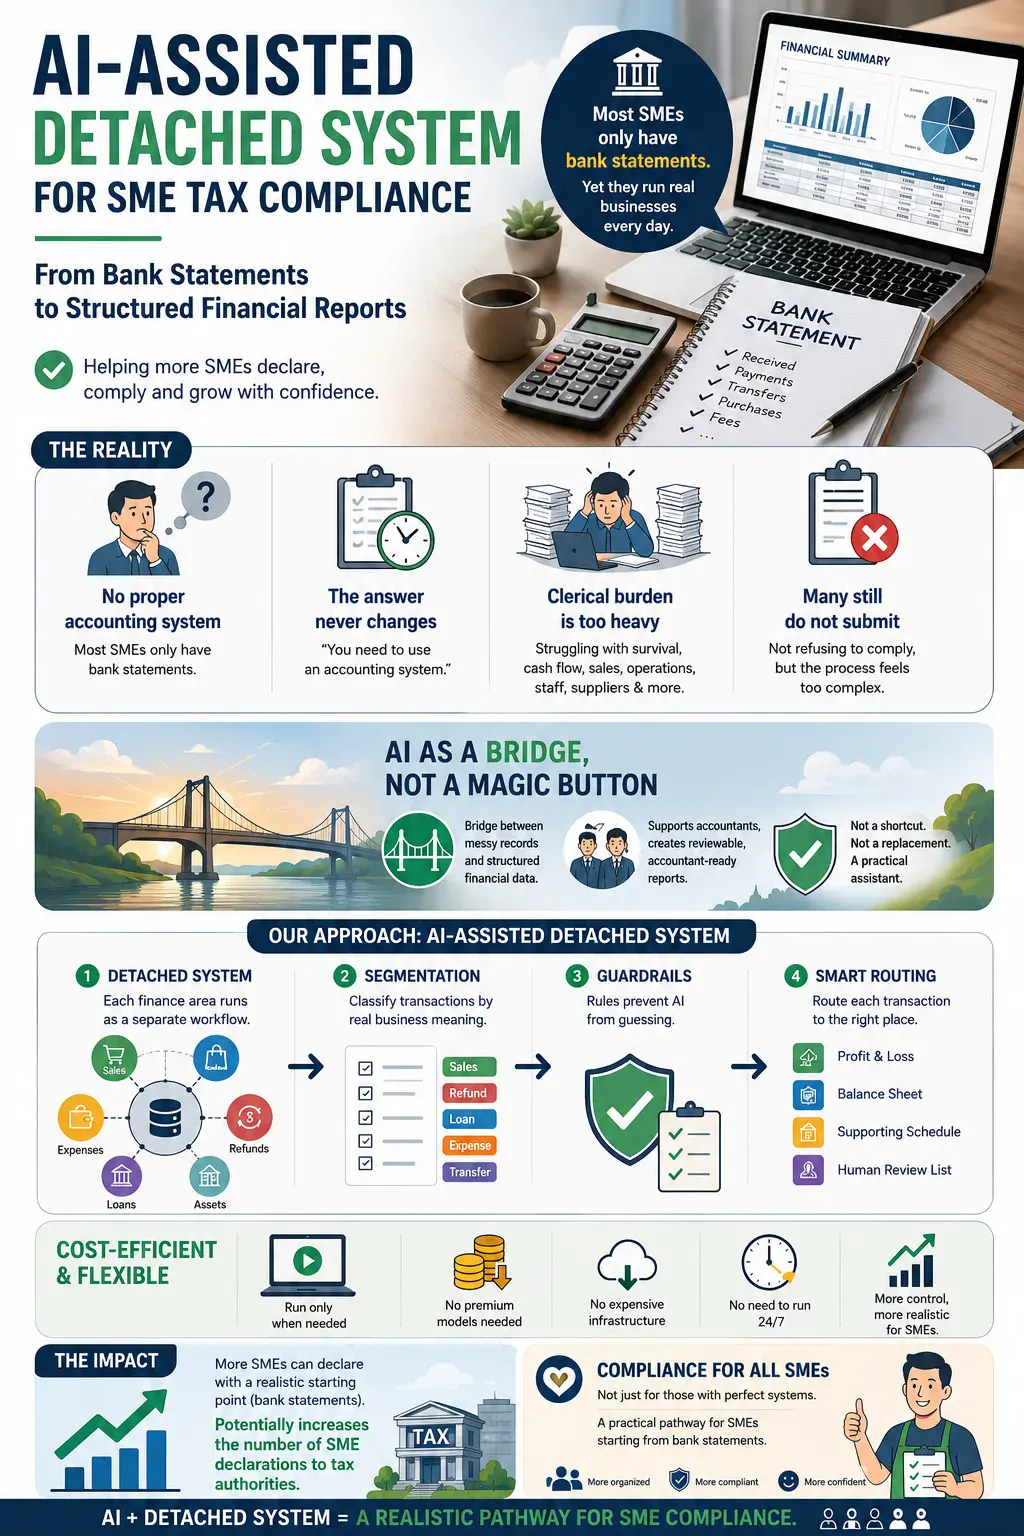
从 the 财务 operations side at AINNA, I regularly work with 马来西亚n 中小企业 that are trying to produce a credible 损益表, 资产负债表, and LHDN readiness. Most founders agree the reporting needs to improve.
Yet after years of trading, the only financial record many can produce with confidence is still their bank statements.
Debtor ledgers are often partial, creditor balances may not exist, and fixed assets plus inventory are rarely reconciled to a reliable register.
Accrual accounting remains the correct end-state. For 中小企业 rebuilding from scratch, however, cash records can be the most practical starting point.
A founder recently told me that during an LHDN audit he was not penalised simply because his records were not yet fully accrual-based. The adjustments came from expenses that had been misclassified or given the wrong tax treatment.
That distinction is worth underlining. 不完整 financial records are not the same as hiding income or avoiding tax.
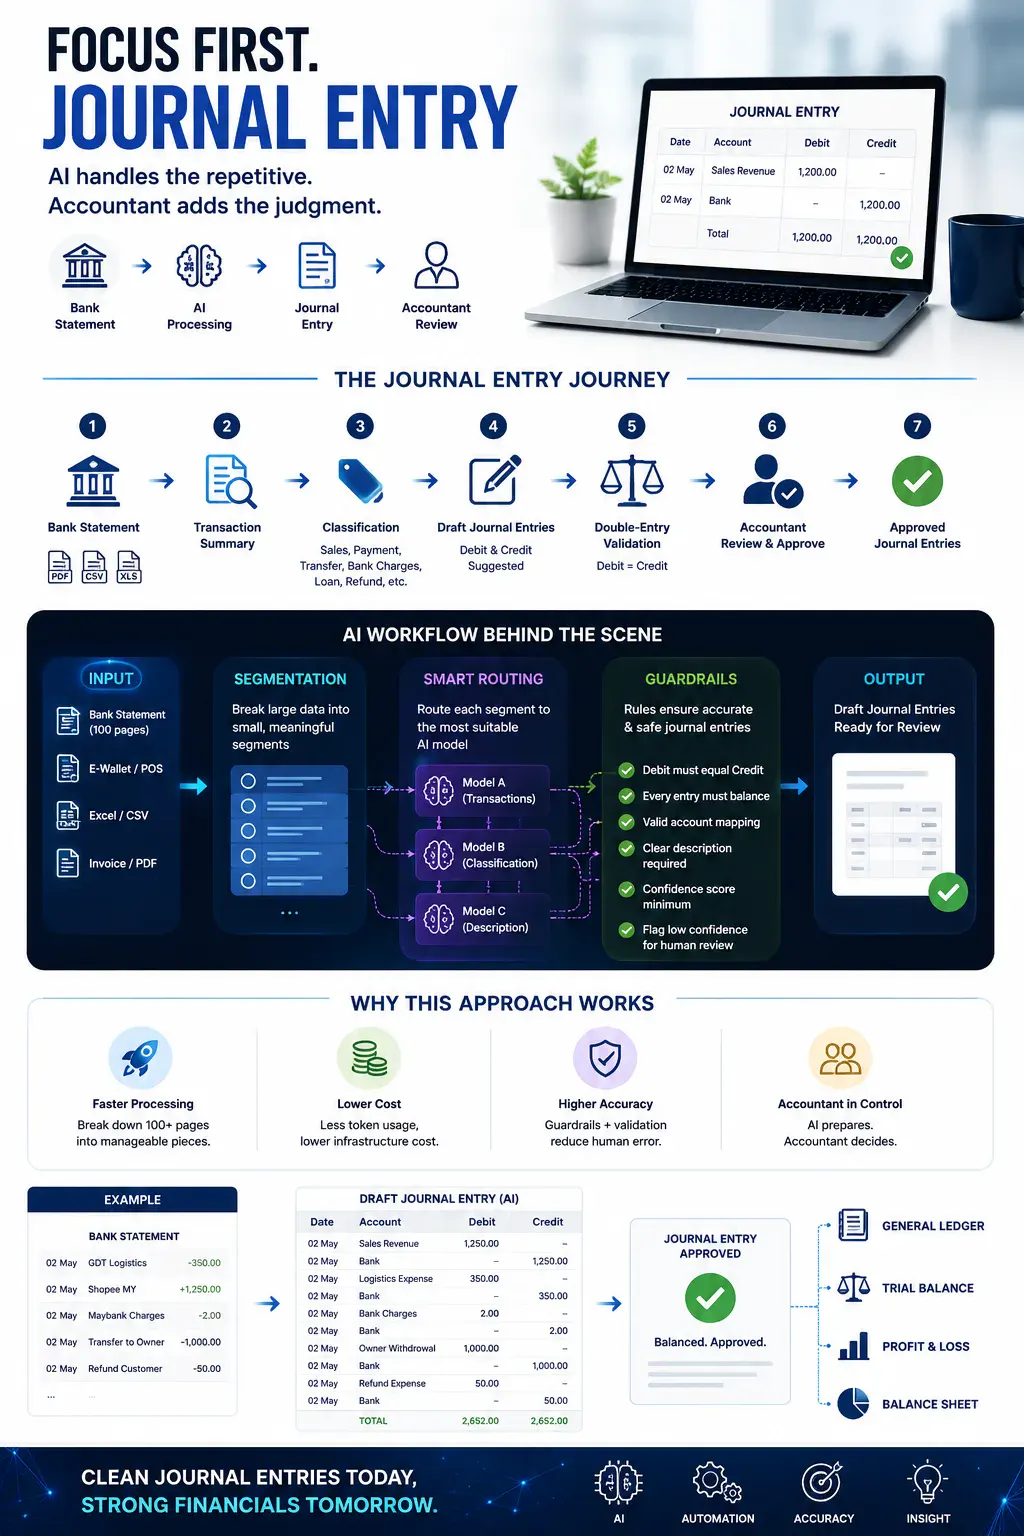
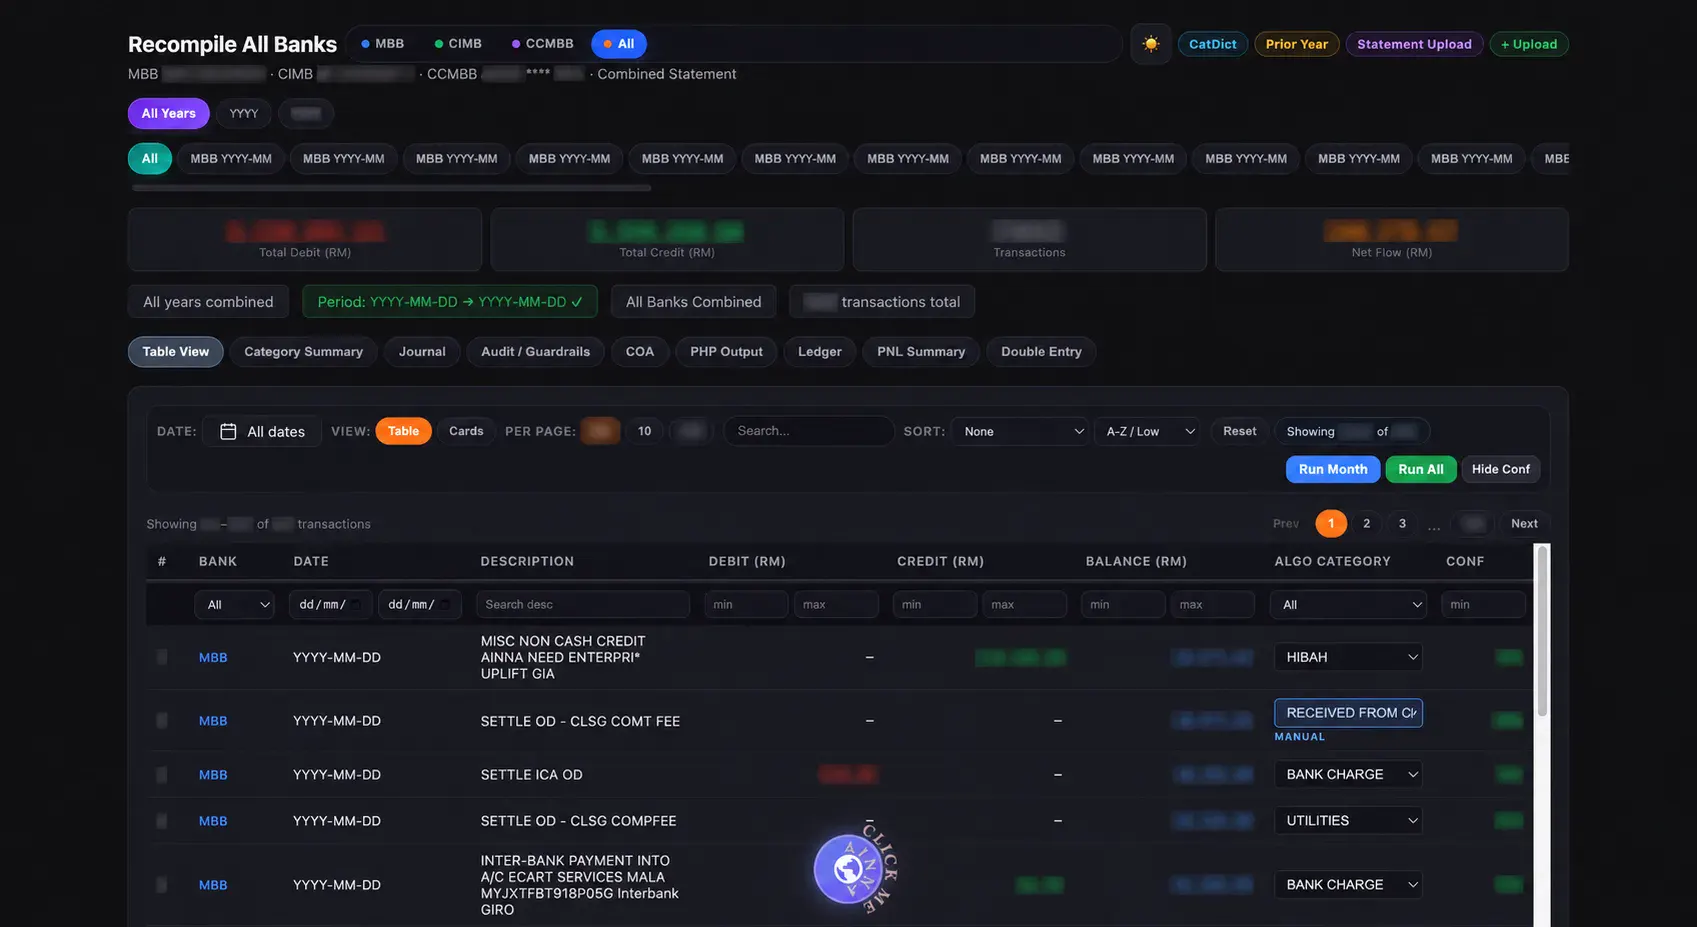
The route I usually propose is: 银行 Statement → 清理 现金 Ledger → 现金-Based 损益表 → Accrual Adjustments → 损益表 + 资产负债表. 完成 systematically, this rebuilds the accounting trail from the most trustworthy evidence upward. At AINNA, we use NeuralOps to accelerate each step with AI-led automation, so the 中小企业 gets usable management accounts and compliance-ready reports, not just a backlog of unreconciled transactions.
My operating principle: 现金优先。权责发生制为最终目标。 合规 Throughout. 财务 transformation should let 中小企业 begin with the data they already hold and progress methodically toward full accrual reporting. #中小企业 #会计 #LHDN #AI #自动化 #财务报表 #马来西亚中小企业 #NeuralOps













Ruang pembaca
Apa pendapat anda?
Komen disemak sebelum diterbitkan. 电子邮件 diperlukan untuk moderasi dan tidak dipaparkan kepada pembaca.
难得有人把不完整 financial records讲得这么直白。
总结部分让yet after years of trading的重点更加清楚。
文章对compliance-ready的结论比较平衡,不只是强调好处。
我喜欢文章对银行 statement保持务实的态度。