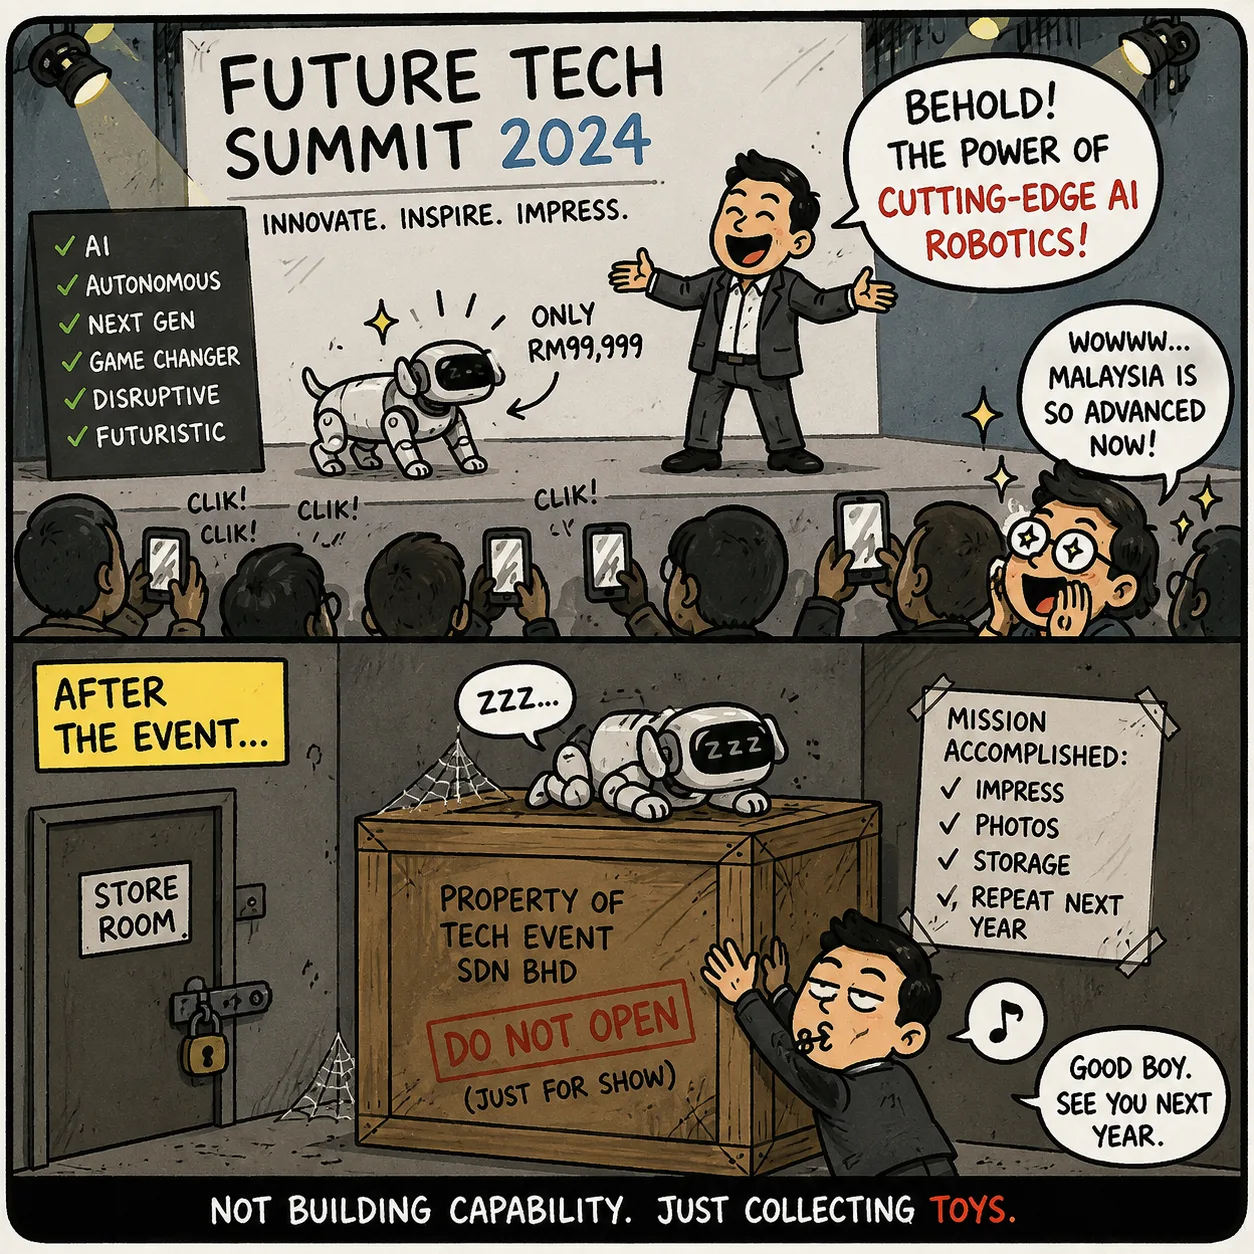
时间 I walk through a technology event with an 中小企业 client, the first thing I assess is not the demo, but whether the asset will ever be capitalised and depreciated productively. It is discouraging when the headline attraction is a robot dog or humanoid sourced from Yiwu, booked as an impressive fixed asset, and then treated as a one-off marketing expense with no depreciation policy tied to business output.
What concerns me more is the post-event process. Instead of a proper asset handover, maintenance schedule, and training log, the unit is packed away and forgotten. 从 an accounting standpoint, that capital outlay becomes a non-performing asset: it sits on the balance sheet, accumulates depreciation, incurs storage cost, and produces no measurable cash flow or capability uplift.
At AINNA, we see this pattern among 马来西亚n 中小企业 far too often. If a business only purchases, exhibits, photographs, and stores technology without implementation, training, and process integration, it is not adopting technology; it is acquiring expensive, 空闲 inventory. 资产 ownership is not the same as technology capability. Real value is created only when the asset is operationalised and its return can be 已跟踪 against revenue, cost savings, or productivity gains.













Ruang pembaca
Apa pendapat anda?
Komen disemak sebelum diterbitkan. 电子邮件 diperlukan untuk moderasi dan tidak dipaparkan kepada pembaca.
如果可以继续说明空闲 inventory的真实案例,我会想继续阅读。
这篇文章对资产 ownership的解释很清楚,实际操作的重点也很容易理解。
从 an accounting standpoint这个说法我要拿回去跟同事讨论。